

Dave: Credit, Cash & Money App
by Dave Operating LLC
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
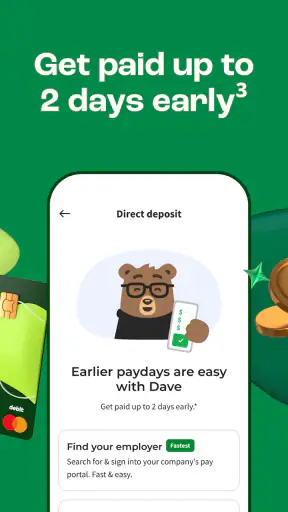
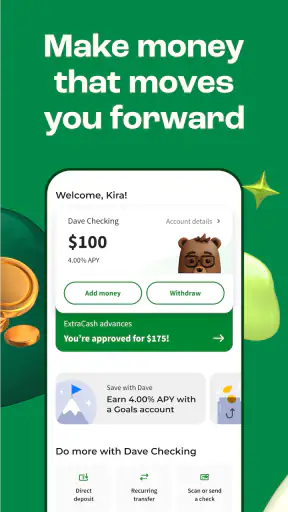
 Analysis by Getfullapps
I approach cash-advance apps with a little more caution than ordinary budgeting tools, because the useful part is often tied to sensitive financial decisions. Dave is built for that specific moment: you need money before your next payday and want to check an option from your phone rather than rely on a credit card or a traditional loan application. After spending time with the app, I found its appeal easy to understand, but I also think it works best when treated as a short-term emergency tool rather than a routine way to stretch every paycheck.
Dave is a free finance app from Dave Operating LLC, available for Everyone and supported on operating systems from version 9 onward. It has reached over ten million installs, with a 4.7 average from around 612 thousand ratings and roughly 232 thousand written reviews. Those figures show that it has attracted a large audience, although popularity alone should not replace careful attention to the terms and choices shown inside the account.
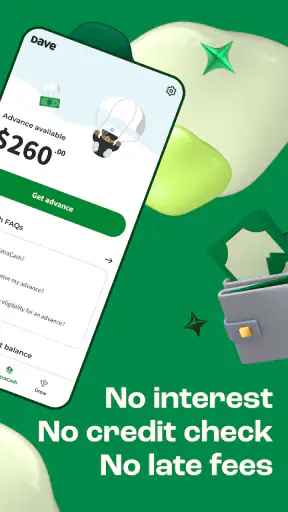
The central promise is straightforward: access to up to 500 before payday, without a credit check and without interest. That can sound reassuring if an unexpected bill arrives, but the important question is not simply whether the app can provide money. It is whether the timing, repayment arrangement, account permissions, and any optional choices fit your situation. That is where I think Dave deserves a closer look.
How Dave fits into a real financial emergency
The most convincing use case is a small, clearly defined gap between today and your next reliable income. Imagine your car needs a necessary repair on a weekday, your pay is several days away, and you have already checked your budget. In that situation, an app that lets you explore a cash advance from your phone may be more practical than applying for a conventional loan, putting the expense on a high-interest credit card, or asking someone close to you for help.
I would not use it to cover a recurring shortfall without first examining why the shortfall keeps happening. A cash advance can solve the immediate timing problem while leaving the monthly budget unchanged. If rent, utilities, groceries, and transportation regularly consume more than your income, repeatedly moving money forward can make the next payday feel even tighter. Dave is more sensible for an isolated disruption than for a permanent income-and-expense mismatch.
This is also where the “no credit check” aspect matters. Someone with limited credit history may find a traditional personal loan difficult or may not want a hard credit-based process for a small need. Dave’s approach is aimed at a different kind of assessment, centered on the account and financial information needed to operate the service. That does not make an advance free money, and it does not remove the need to understand repayment timing.
Compared with a credit card, the main advantage is that the product is designed around a short cash gap rather than an open-ended revolving balance. Compared with overdraft protection from a bank, the experience may feel more focused on the advance itself. Compared with borrowing from a friend, it offers privacy and a digital workflow. The trade-off is that you are placing a financial service inside an app, so account access, data choices, and the exact repayment details deserve more attention than they might receive during a stressful moment.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What I check before requesting money
My first step would be to decide the smallest amount that actually solves the problem. If a bill is 80, requesting the maximum available simply because it appears on screen creates unnecessary pressure later. I would also write down the date and amount of the expected income before starting. That simple preparation makes it easier to judge whether the repayment schedule is realistic instead of accepting an offer impulsively.
I would then read every screen related to timing, eligibility, repayment, and optional services. Financial apps often present a quick path for users who already know what they want, but speed can hide choices that deserve a slower look. I pay particular attention to whether a faster delivery option, membership-related choice, or voluntary contribution is selected or merely displayed. A visible choice is not automatically a required one.
One practical habit is to take a moment before confirming and ask, “What will leave my account, and when?” That question is more useful than focusing only on the amount arriving today. A cash advance should fit into the full pay cycle, including bills that are scheduled before the next income deposit. If the answer is unclear, I would stop and review the account rather than proceed under pressure.
Trust starts with the account setup
Because Dave handles financial information, I would judge trust through what the app visibly asks me to do and what choices it gives me, not through its friendly design alone. During setup, I would read the explanations surrounding linked accounts, identity details, notifications, and any permissions requested by the phone. Each request should have a clear reason connected to the service I am trying to use.
I also prefer to connect only the account that is necessary for the intended task. If an app presents several ways to provide information, I would choose the narrowest practical route and avoid granting access simply because it makes setup faster. This is not a criticism of Dave specifically; it is a sensible rule for any finance app. The more financial context an app can see, the more important it becomes to understand the purpose and control options attached to that access.
Another trust signal is whether the app lets me review my profile and account choices after registration. I want to know where personal details, linked accounts, notifications, and service preferences can be managed. If I cannot quickly locate those controls, I treat that as a reason to slow down. A polished onboarding flow is useful, but a trustworthy financial tool should also make the exit and adjustment paths understandable.
Dave Operating LLC is the developer behind the app, and the current version is 4.6.0. I would keep the app updated through the official store because finance software should not be left on an old build unnecessarily. I would also protect the phone itself with a screen lock and avoid opening financial screens on shared devices. Those steps are basic, but they matter just as much as the app’s visible interface.
Permissions and sensitive moments
The most sensitive point is not the moment when money appears on the screen. It is the moment when I decide what financial information to connect and what access to maintain afterward. Before approving anything, I would inspect the permission prompt and the accompanying explanation. If the wording is too broad or I do not understand why a permission is needed, I would postpone the setup and investigate through the app’s own account and privacy screens.
I would also be careful with notifications. Payment reminders can be useful, especially when a repayment date matters, but notifications may reveal financial information on a lock screen. I prefer previews that show little detail and a device setting that hides sensitive content until the phone is unlocked. This gives me the reminder without broadcasting the nature of the transaction to anyone nearby.
When linking an account, I would avoid doing it over public Wi-Fi and would not save screenshots containing balances, account numbers, or confirmation details. I would review the connected account afterward and check that the expected information is being used for the intended purpose. These are small actions, yet they reduce the chance of treating a financial app like an ordinary shopping or entertainment download.
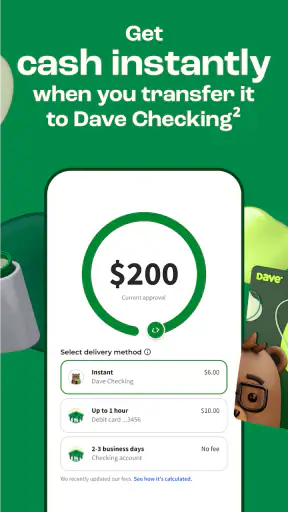
I would also separate the question of access from the question of convenience. A feature that makes an advance arrive faster may be attractive during an emergency, but faster is not automatically better if it adds a cost or reduces the time available to reconsider. I would compare the available delivery choices on the confirmation screen and select only what I genuinely need.
Where user choice matters most
Dave’s value depends on giving the user enough control to make an informed decision. I look for clear explanations of the amount, timing, repayment process, and any optional payment or membership-related selections. If a screen uses a button that combines several choices, I read the smaller text before tapping. In a financial app, the difference between “continue” and “confirm” can be important.
I would never assume that a voluntary contribution, optional upgrade, or faster service is required just because it appears prominently. The safest approach is to inspect the wording and, where possible, choose the basic route first. If the app makes an optional choice difficult to decline, that would lower my confidence even if the core advance itself were useful.
Account control also means knowing what to do after the emergency has passed. I would review whether the linked account is still needed, adjust notifications that are no longer useful, and look for account-management tools before deleting the app. Removing an icon does not necessarily explain what happens to an account or connected information. I prefer to use the in-app controls first and keep a record of any confirmation shown.
If a repayment is approaching and my income has changed, I would contact support through the official route visible in the app rather than ignore the situation. Avoiding the app will not make the obligation disappear. The important point is to understand the available options early, while there is still time to plan around the account balance.
Three practical lessons I would keep in mind
First, I would use Dave as a bridge, not as part of my normal spending system. Before requesting anything, I would create a one-line repayment plan: expected income, repayment amount, and the bills that must remain untouched. If those numbers do not fit together, the advance is not solving the real problem.
Second, I would treat the maximum amount as a ceiling rather than a target. The ability to request up to 500 does not mean taking that much is sensible. A smaller advance reduces the amount that has to be recovered from the next pay cycle and makes it easier to keep essential expenses protected.
Third, I would review the app after each use instead of leaving every setting unchanged. That means checking notifications, connected-account choices, delivery selections, and any optional feature presented during the process. This is a less obvious but important distinction between using a finance app deliberately and allowing its default path to make decisions for me.
A fourth lesson is to compare the total practical cost, not just the word “interest.” An option can be interest-free and still involve choices that affect convenience, timing, or voluntary payments. I would look at the complete confirmation screen and compare it with alternatives already available to me, such as delaying a nonessential purchase, using savings, asking an employer about pay timing, or choosing a conventional credit product with terms I fully understand.
Who should use it, and who should skip it
I think Dave is best suited to an adult who has a dependable upcoming income, understands the repayment timing, and needs a limited amount for a genuine short-term interruption. It may also appeal to someone who wants to explore a cash option without relying on a traditional credit check. The free download and Everyone rating make it easy to consider, but ease of access should not be confused with suitability.
I would skip it if my income is unpredictable, if I am already behind on several obligations, or if I need money for an expense that will repeat next month. I would also avoid using it to fund discretionary purchases that can wait. In those situations, a nonprofit debt counselor, a structured budget review, an employer-based option, or a carefully compared conventional loan may be more appropriate.
Someone who values complete separation between a mobile app and their banking information may also prefer a different solution, even if Dave offers a convenient workflow. The right choice depends on how comfortable the user is with the account connection and the controls displayed during setup. I would not recommend proceeding until those choices feel understandable.
My cautious verdict
Dave is useful when the problem is timing, not a lack of a workable financial plan. I like the direct focus on a small pre-payday need, the absence of a credit check in its core promise, and the fact that the app is free to install. Its strong user adoption and 4.7 average suggest that many people find the service valuable, but I would still make my decision from the actual account screens rather than from popularity.
The limitations are equally important. A fast cash option can encourage a rushed decision, and any repayment taken from the next income cycle can make ordinary bills harder to manage. The app also requires the kind of careful attention I expect from a financial service: review permissions, understand connected accounts, distinguish optional choices from required steps, and protect notifications and login access.
My recommendation is conditional but positive. If you have a clear repayment plan and a one-time need, Dave is worth examining as an alternative to a credit card, overdraft, or informal borrowing. If you are using it to cover the same gap repeatedly, I would choose a broader budgeting or debt-support solution instead. In my view, the safest way to use it is to request only what is necessary, read every confirmation screen, and reclaim control of the account settings once the emergency is over.
For readers comparing versions, the app was released on April 24, 2017, and its current version is 4.6.0. It remains a finance tool rather than a general budgeting companion in my assessment: its strongest value appears when a specific short-term cash problem needs attention. Used with that narrow purpose and with deliberate privacy and repayment checks, it can be a practical option. Used casually, it can make a temporary shortage feel easier today while making the next payday more complicated.
Pros
- User-friendly interface for easy navigation.
- Quick cash advances with no hidden fees.
- Seamless bank account linking process.
- Automatic budgeting feature helps track expenses.
- No credit check required for advance eligibility.
Cons
- Limited cash advance amount for new users.
- Requires a monthly subscription fee.
- Occasional app glitches reported by users.
- Limited customer support options available.
- Not all banks are supported for linking.
FAQs for Dave: Credit, Cash & Money App
What is Dave: Credit, Cash & Money App?
Dave is a financial management app designed to help users manage their expenses, avoid overdraft fees, and build credit. It offers features like cash advances, budgeting tools, and the ability to connect directly to your bank account. The app is available for both Android and iOS devices.
How does the cash advance feature work in Dave?
Dave allows users to request a cash advance to cover small expenses and avoid overdraft fees. Once you connect your bank account to the app, it analyzes your spending habits and offers advances based on your predicted needs. The cash advance is typically available to your account within a day.
Is there a fee to use Dave?
Dave charges a subscription fee of $1 per month, which grants access to its full suite of features, including budgeting tools and cash advances. However, the app does not charge interest on cash advances, though tips are optional and appreciated for faster service.
How does Dave help with budgeting?
Dave provides a comprehensive budgeting tool that tracks your income and expenses. By connecting to your bank account, it categorizes your spending and provides insights into your financial habits. This helps users set financial goals and manage their money more effectively.
Can Dave help improve my credit score?
Yes, Dave offers a credit-building feature that reports your payment history to major credit bureaus. By maintaining a positive balance and making regular payments, users can boost their credit score over time. This feature is especially beneficial for those looking to establish or improve their credit history.

Dave: Credit, Cash & Money App
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@dave.com, visit https://dave.com, or review their https://www.dave.com/privacy.










